Homeowners insurance in Ashland, Ohio: what local buyers need to know
If you own a home in Ashland, Ohio, homeowners insurance is one of the most important financial decisions you will make. Ashland sits in north-central Ohio, where cold winters, spring thunderstorms, and occasional hail events can turn a good year into a very expensive one without the right coverage. Whether you just bought your first home near Brookside Park or you have owned your place on the east side for twenty years, understanding what your policy actually does and does not cover can save you thousands of dollars when a claim happens.
What a standard homeowners policy covers in Ohio
Most Ohio homeowners policies follow the HO-3 form, the industry standard for owner-occupied single-family homes. It breaks down into four main coverage areas.
- Dwelling coverage pays to repair or rebuild the physical structure of your home, including walls, roof, attached garage, and built-in appliances, when damage is caused by a covered peril such as fire, wind, hail, or lightning.
- Other structures coverage covers detached garages, fences, sheds, and similar structures. It typically defaults to 10 percent of your dwelling limit.
- Personal property coverage reimburses you for furniture, electronics, clothing, and other belongings that are damaged or stolen. Most policies default to actual cash value, but you can upgrade to replacement cost so depreciation does not reduce your payout.
- Liability coverage pays legal defense and settlement costs if someone is injured on your property or you accidentally damage someone else's property. A standard limit is $100,000 , but many Ashland homeowners upgrade to $300,000 or add a personal umbrella policy for broader protection.
- Loss of use (additional living expenses) covers hotel stays, restaurant meals, and other temporary living costs while your home is being repaired after a covered loss.
Ohio does not legally require homeowners insurance the way it requires auto insurance, but virtually every mortgage lender does. Even if you own your home free and clear, going without coverage rarely makes financial sense.
Local risks Ashland homeowners should plan for
Ashland County experiences weather patterns that put real stress on homes. Knowing those risks before you buy a policy helps you select the right limits and endorsements rather than discovering gaps after a loss.
Wind and hail
Ohio ranks among the top states for hail frequency, and Ashland is no exception. Spring and early summer thunderstorms regularly push golf-ball-size hail across Richland and Ashland counties. A standard HO-3 policy covers hail damage, but pay close attention to how your deductible is worded. Some carriers have introduced separate wind and hail deductibles expressed as a percentage of your dwelling limit rather than a flat dollar amount. On a $250,000 home with a 2 percent wind/hail deductible, you would be responsible for the first $5,000 of any hail claim, not a $1,000 flat deductible. Ask your agent to confirm exactly how this is structured in your policy. You can also read more about how hail claims work in our post on Ohio hail damage and home insurance claims.
Winter weather and ice dams
Ashland winters bring freeze-thaw cycles that are hard on roofs and gutters. Ice dams form when heat escapes through the attic, melts snow on the roof, and that water refreezes at the eave line. When it backs up under shingles, you can end up with water damage to ceilings, insulation, and interior walls. A standard policy covers the resulting interior water damage, but it generally will not pay to fix the ice dam itself or any underlying insulation problem that caused it. That distinction matters when you are filing a claim.
Flooding
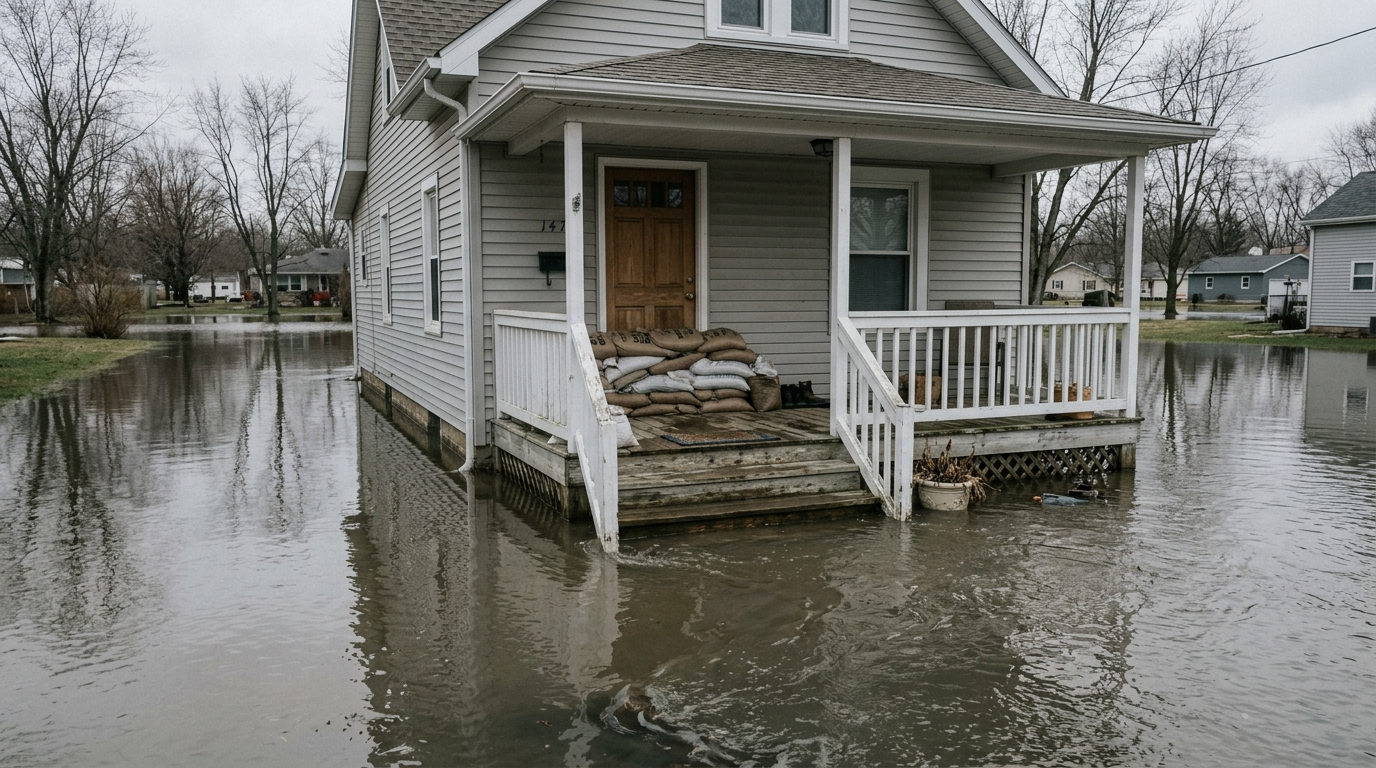
This surprises many homeowners: a standard HO-3 policy does not cover flooding. Not from a creek rising, not from a storm drain backing up into your basement, not from overland flow during a heavy rain. Ashland has low-lying areas near the Black Fork Mohican River and its tributaries where flood exposure is real. If your home is in or near a flood zone, a separate flood policy through the National Flood Insurance Program (NFIP) or a private carrier is worth serious consideration. We cover this topic in our post on homeowners vs. flood insurance in Ohio, and you can explore your flood coverage options at our personal flood insurance page.
How much does homeowners insurance cost in Ashland, Ohio?
Ohio homeowners insurance rates are generally below the national average. The statewide average runs roughly $1,200 to $1,600 per year for a typical single-family home, though your actual premium depends on several factors specific to your property and situation.
- Dwelling replacement cost: insurers base your dwelling limit on what it would cost to rebuild your home from scratch at current labor and material prices, not its market value. Construction costs have risen sharply since 2020, so older policies may be underinsured.
- Roof age and material: a newer roof with architectural shingles often qualifies for a better rate than a 20-year-old three-tab shingle roof. Some carriers will not write new policies on homes with roofs older than 15 to 20 years.
- Claims history: your personal claims history and the property's prior claims history both factor into pricing. Even a water claim three years ago can affect your rate today.
- Credit score: Ohio allows carriers to use a credit-based insurance score as a rating factor. Improving your credit can meaningfully lower your premium over time.
- Deductible choice: raising your all-peril deductible from $1,000 to $2,500 can reduce your annual premium by 10 to 20 percent depending on the carrier.
For a deeper look at statewide cost factors, see our full breakdown of Ohio homeowners insurance costs.
Bundling home and auto: a practical way to lower your total bill
One of the most reliable ways Ashland homeowners reduce their overall insurance costs is by bundling home and auto policies with the same carrier. Multi-policy discounts typically range from 10 to 25 percent across both policies. A household paying $1,400 for homeowners and $1,200 for auto could save $260 to $650 per year just by placing both with the same company through an independent agent who can shop multiple carriers at once.
Bundling also simplifies your life: one renewal date, one agent relationship, and one call when you have a question. If you want to see how the math works in practice, our post on bundling home and auto and how much you can really save walks through real scenarios. You can also review your auto coverage on our car insurance in Ashland, Ohio page.
Coverage gaps that catch Ashland homeowners off guard
Standard policies have limits and exclusions that many homeowners discover for the first time when they file a claim. A few of the most common surprises are below.
Sewer and drain backup
If your sewer line backs up and floods your basement, a standard policy almost never covers it. This coverage is available as an add-on endorsement, often for $50 to $150 per year . Given how many Ashland homes have older sewer laterals, it is worth adding.
Jewelry, art, and valuables
Personal property coverage caps theft and loss of jewelry at $1,000 to $2,500 under most standard policies. An engagement ring worth $8,000 is only covered up to that sub-limit. A scheduled personal property endorsement (sometimes called a floater) covers individual items at their appraised value with no deductible and broader covered perils. See our jewelry insurance page for details.
Business equipment at home
If you run a home-based business or keep business equipment at your house, standard homeowners coverage typically limits business property to $2,500 or less and does not cover business liability. A home business endorsement or a separate business policy fills that gap.
Actual cash value vs. replacement cost on personal property
If your policy pays personal property claims at actual cash value, a five-year-old couch that cost $1,200 might settle for $300 after depreciation. Upgrading to replacement cost adds a modest premium but pays what it actually costs to replace the item today.
What to look for when comparing policies
Not all homeowners policies are the same, even when the premium looks similar. When reviewing quotes, focus on these specifics:
- Guaranteed replacement cost vs. extended replacement cost: these provisions pay above your dwelling limit if construction costs have risen and your coverage amount is no longer enough to fully rebuild.
- Ordinance or law coverage: if your home is damaged and local building codes require upgrades during repair (new electrical, updated plumbing), this endorsement covers the extra cost. It is especially relevant for older Ashland homes built before modern code requirements.
- Loss assessment coverage: relevant if you belong to a homeowner association with shared property. If the HOA's property is damaged and the association assesses each member, this coverage helps pay your share.
- Claim service reputation: a carrier's financial strength rating (A.M. Best A or better) and claims satisfaction scores matter as much as price. The cheapest policy that takes three months to pay a claim is not a bargain.
Get the right homeowners insurance coverage in Ashland, Ohio
At The Hutch Agency , we are an independent insurance agency, which means we shop your coverage across multiple carriers rather than pushing a single company's product. That gives you an honest comparison of price and coverage, not just the best deal one company is willing to offer on a given day.
We work with homeowners in Ashland and the surrounding area. We know the local risks, the carriers who write in this market, and the policy details that matter when you actually need to file a claim. If your renewal is coming up, your home has had significant renovations, or you have never had your current policy reviewed, now is a good time to take a look.
Call us at (740) 886-7200 or visit our contact page to get a homeowners insurance quote. It costs nothing to compare, and it could save you a meaningful amount every year while making sure you have the right protection in place.