Senior bundle insurance in Ohio: how home, auto, and life work together
If you are 55 or older in Ohio and still paying for home, auto, and life insurance through separate companies, there is a good chance you are leaving real money on the table every year. Senior bundle insurance in Ohio combines those coverages under one or two carriers, unlocking multi-policy discounts that can reach 15 to 25 percent on home and auto premiums alone. For a retired household in Lawrence County or Gallia County on a fixed income, that difference can mean several hundred dollars back annually.
What bundling actually means for Ohio seniors
Bundling means purchasing two or more insurance policies from the same carrier so that carrier rewards your loyalty with a discount on each policy. The most common pairing is home plus auto , but seniors often have a third piece: life insurance. Some carriers will price all three together, while others apply the home-auto discount and treat life separately. Either way, consolidating with one company, or one independent agent who manages multiple carriers, simplifies your billing, your renewal dates, and your claims experience.
Ohio has no law requiring you to bundle, and no regulation caps what a carrier can charge for individual policies versus bundled ones. The discount is purely a carrier business decision, which is why rates vary so widely from one insurer to the next. That variation is exactly why shopping through an independent agent matters more for seniors than for almost any other demographic.
The home insurance piece
Ohio homeowners insurance for seniors typically covers the dwelling, personal property, liability, and additional living expenses if a covered loss makes the home uninhabitable. In our part of Ohio and the Tri-State area, wind and hail damage is the most common claim driver, with ice damming in January and February a close second. If you have owned your home for 20 or 30 years, your replacement cost may be significantly higher than what your current coverage reflects, especially given construction cost increases since 2020. A bundled review is a good time to verify your dwelling limit is accurate. You can find more detail on what a standard homeowners policy covers in our homeowners insurance 101 guide.
The auto insurance piece
Ohio requires minimum liability limits of 25/50/25 ($25,000 bodily injury per person, $50,000 per accident, $25,000 property damage). Those minimums have not changed in years and are widely considered too low for real-world accidents. Many seniors drive fewer miles in retirement, which opens the door to low-mileage discounts on top of the bundle discount. Some carriers also offer mature driver credits for completing a defensive driving course, which costs very little and can knock another 5 percent off the premium. Stacking a bundle discount, a low-mileage discount, and a mature driver credit is not unusual.
The life insurance piece
Life insurance in a senior bundle conversation usually means one of two products: term life or permanent (whole or universal) life . Most seniors in their 60s and early 70s who still carry life coverage are either protecting a surviving spouse's income, covering a remaining mortgage, or leaving a specific legacy amount. If you are past the income-replacement need and the mortgage is paid, a smaller final expense whole life policy may be the right fit and can often be quoted alongside home and auto for a cleaner package. For a deeper breakdown of which type of policy fits which goal, see our post on term life vs. whole life insurance.
How much can Ohio seniors actually save by bundling?
The honest answer is that it depends on which carriers you qualify for, your property's location and age, your driving record, and your health for life insurance purposes. That said, here are realistic ranges based on what independent agents in Ohio see:
- Home plus auto bundle discount: typically 10 to 20 percent off each policy with most standard carriers. On a combined annual premium of $3,000, that is $300 to $600 saved per year.
- Low-mileage auto discount: an additional 5 to 15 percent if you drive fewer than 7,500 miles per year, which many retired Ohioans do.
- Mature driver course credit: 5 to 10 percent on the auto policy from most carriers, available to drivers 55 and older who complete an approved course.
- Loyalty credits: some carriers add a percentage back for each consecutive year you remain with them, compounding over time.
- Claims-free discount: if you have gone three to five years without a claim, many carriers apply an additional credit at renewal.
Stack several of those together on a clean record and the savings are meaningful. Our post on how much bundling home and auto can really save walks through specific scenarios with the math laid out.
Pitfalls seniors should watch for when bundling
Bundling is not always the right move without doing the math first. Here are the situations where it can backfire:
- Carrier A wins on home, carrier B wins on auto. Sometimes the cheapest total cost is actually two separate companies. An independent agent runs both scenarios before making a recommendation.
- Bundling with a carrier that is weak on claims. A discount means nothing if the company fights every claim or is slow to pay. Check the Ohio Department of Insurance's complaint index for any carrier you are considering before you commit.
- Letting coverage limits slide to keep the bundle premium low. Some seniors accept lower dwelling limits or higher deductibles to make the bundle price look attractive. That is a false saving. If a fire destroys a home in South Point or Proctorville, an underinsured policy creates a financial crisis.
- Forgetting to shop at renewal. Carrier pricing changes every year. A bundle that was the best deal three years ago may not be now. Seniors on fixed incomes benefit most from an agent who shops the market at every renewal cycle, not just at the initial quote.
- Life insurance medical underwriting. Bundling home and auto is straightforward. Adding life insurance involves a health application. Seniors with certain conditions may find that the life policy they want is either rated (higher premium) or declined by the carrier offering the best home-auto bundle. An independent agent can place the life coverage with a different carrier if needed while still maintaining the home-auto bundle discount elsewhere.
Ohio-specific factors that affect senior bundle pricing
Where you live in Ohio matters more than most people realize. Carriers file separate rate tables by county and ZIP code with the Ohio Department of Insurance. A few things affect senior bundle pricing in our region specifically.
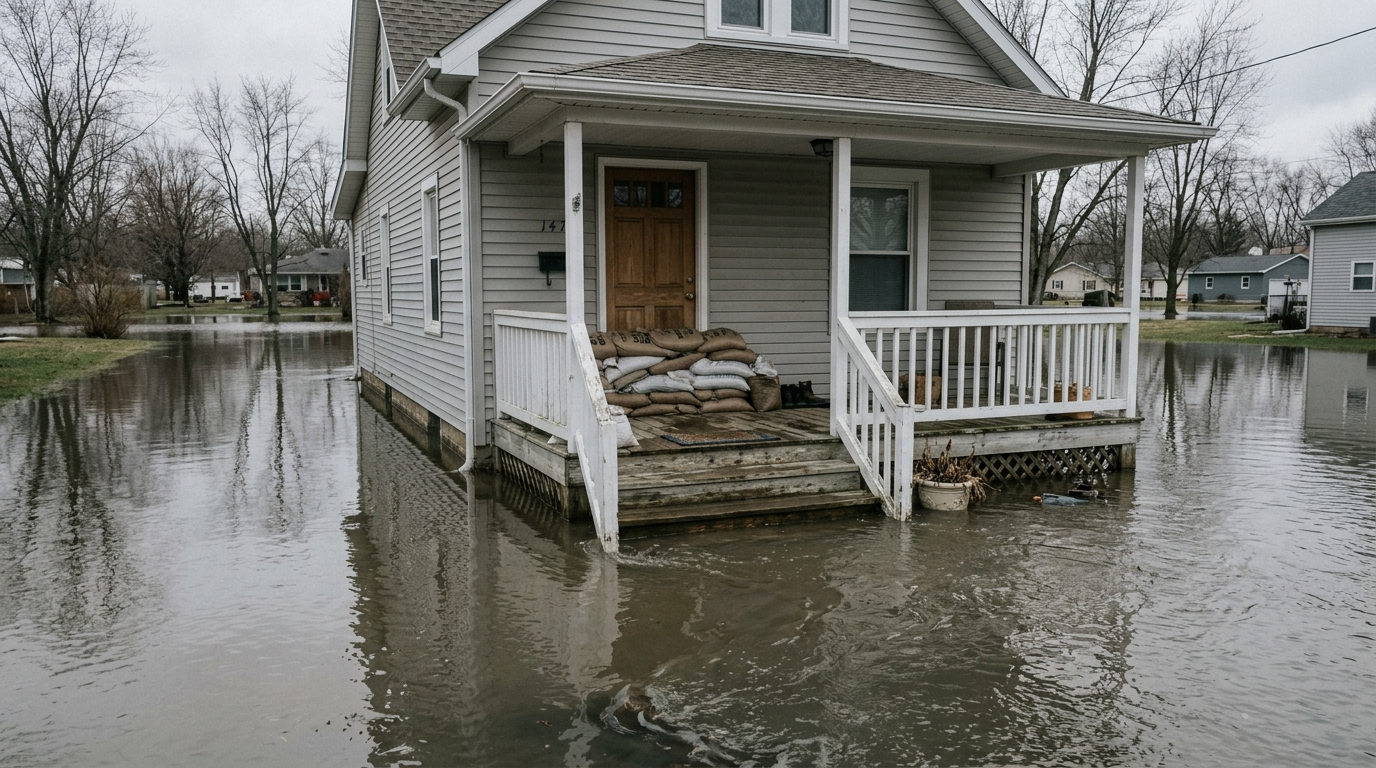
Proximity to the Ohio River. Homes near the river in Lawrence County face elevated flood risk. Standard homeowners policies do not cover flood, so seniors in Chesapeake, South Point, or Rome need to evaluate a separate flood policy regardless of how they bundle their other coverages. See our overview of personal flood insurance in Ohio for what that typically costs and what it covers.
Older home construction. Many seniors in the Tri-State area own homes built in the 1950s through 1970s. Carriers often apply surcharges for knob-and-tube wiring, galvanized plumbing, or roofs past a certain age. A bundle review is a good time to verify that your home's systems are accurately documented, because inaccurate information can create a claim problem later.
Rural roads and driving patterns. Seniors in rural Lawrence, Gallia, or Meigs counties often drive on two-lane state routes with higher deer-collision rates than urban areas. Comprehensive coverage on the auto policy matters more than most people expect in these areas and is worth keeping even on older vehicles with modest market value.
Ohio's auto insurance minimum requirements. The state minimums are a legal floor, not a coverage recommendation. Seniors with assets, a paid-off home, and retirement savings have more to protect than a younger driver just starting out. Higher liability limits cost less than most people assume, and a personal umbrella policy layered on top of a home-auto bundle is one of the most cost-effective ways to protect accumulated assets from a serious liability claim.
When to review your bundle and what to bring to the conversation
The best time to shop a senior bundle is 60 to 90 days before your current policies renew. That window gives you time to compare quotes, ask questions, and make a clean transition without a gap in coverage. Gather the following before you call or meet with an agent:
- Current declarations pages: the one-page summary from each of your existing policies showing limits, deductibles, and annual premium.
- Home details: year built, square footage, roof age and material, and any recent renovations or upgrades.
- Vehicle information: year, make, model, mileage, and your estimated annual mileage going forward.
- Driving history: any accidents or tickets in the past three to five years for every driver on the policy.
- Life insurance goal: a simple statement of what you want the policy to accomplish, whether that is paying off a mortgage, funding a spouse's retirement, covering final expenses, or leaving a specific amount to a beneficiary.
- Claims history: any home or auto claims in the past five years, even ones your current carrier handled without raising your rate.
Bringing these items to a 30-minute conversation with an independent agent cuts the time in half and leads to more accurate quotes. It also helps you avoid the frustrating experience of getting a preliminary quote that changes once the carrier runs your actual history.
Ready to compare senior bundle options in Ohio?
The Hutch Agency is an independent insurance agency serving seniors throughout the Tri-State area of Ohio, West Virginia, and Kentucky. Being independent means we work with multiple carriers and compare their rates and terms side by side on your behalf. We are not locked into one company's pricing or products, so our job is to find the bundle that actually fits your situation.
If you are ready to see what a home, auto, and life bundle could save you this year, visit our contact page to request a quote or reach us directly at (740) 886-7200 . There is no obligation, and most senior bundle comparisons can be turned around quickly once we have your current policy information in hand.